

Non-joint co-sureties: why the aggregate amount of judgments cannot exceed the guaranteed debt
Introduction
Where a creditor has the benefit of several suretyships securing the same debt, a formidable question arises on default by the principal debtor: may the creditor obtain from each surety payment in full of its undertaking, even if the creditor thereby receives in total more than the amount of the secured claim?
The Commercial Chamber of the Cour de cassation, in a judgment of 1 April 2026 (No. 23-23.758, FS-B), gives a clear answer: where the co-sureties (cofidéjusseurs) are not jointly liable to one another and are all sued for payment, the total amount of the judgments given against them cannot exceed that of the principal debt. The solution, based on the accessory nature of suretyship, requires a proportionate division of the debt between the sureties.
For creditors, sureties and their advisers, this judgment is a structuring reminder: suretyship, even where multiple, cannot become a source of enrichment for the beneficiary of the security.
The legal framework: accessory nature and liability for the whole debt
The principle of former Article 2290 of the French Civil Code
Former Article 2290 of the French Civil Code – the substance of which is now found in Article 2296 – lays down one of the most fundamental rules of the law of suretyship: it "may not exceed what is owed by the debtor, nor be entered into on more onerous terms". This text is the direct expression of the accessory nature of the security: the surety's undertaking is necessarily limited by the extent of the principal obligation.
The rule of former Article 2302 of the French Civil Code
Former Article 2302 – now Article 2306 – provides for its part that, where several persons have stood surety for the same debtor for the same debt, "each of them is bound for the whole debt". This text does not distinguish according to whether the co-sureties are or are not jointly liable to one another: even in the absence of horizontal joint liability, each surety remains individually bound for the whole of the guaranteed debt or, where there is a contractual cap, within the limit of its undertaking.
Taken separately, these two texts raise no difficulty. Their interaction becomes problematic, however, where the co-sureties' cumulative undertakings exceed the amount of the principal debt.
The facts and the solution in the judgment of 1 April 2026
A cumulative award greatly exceeding the guaranteed debt
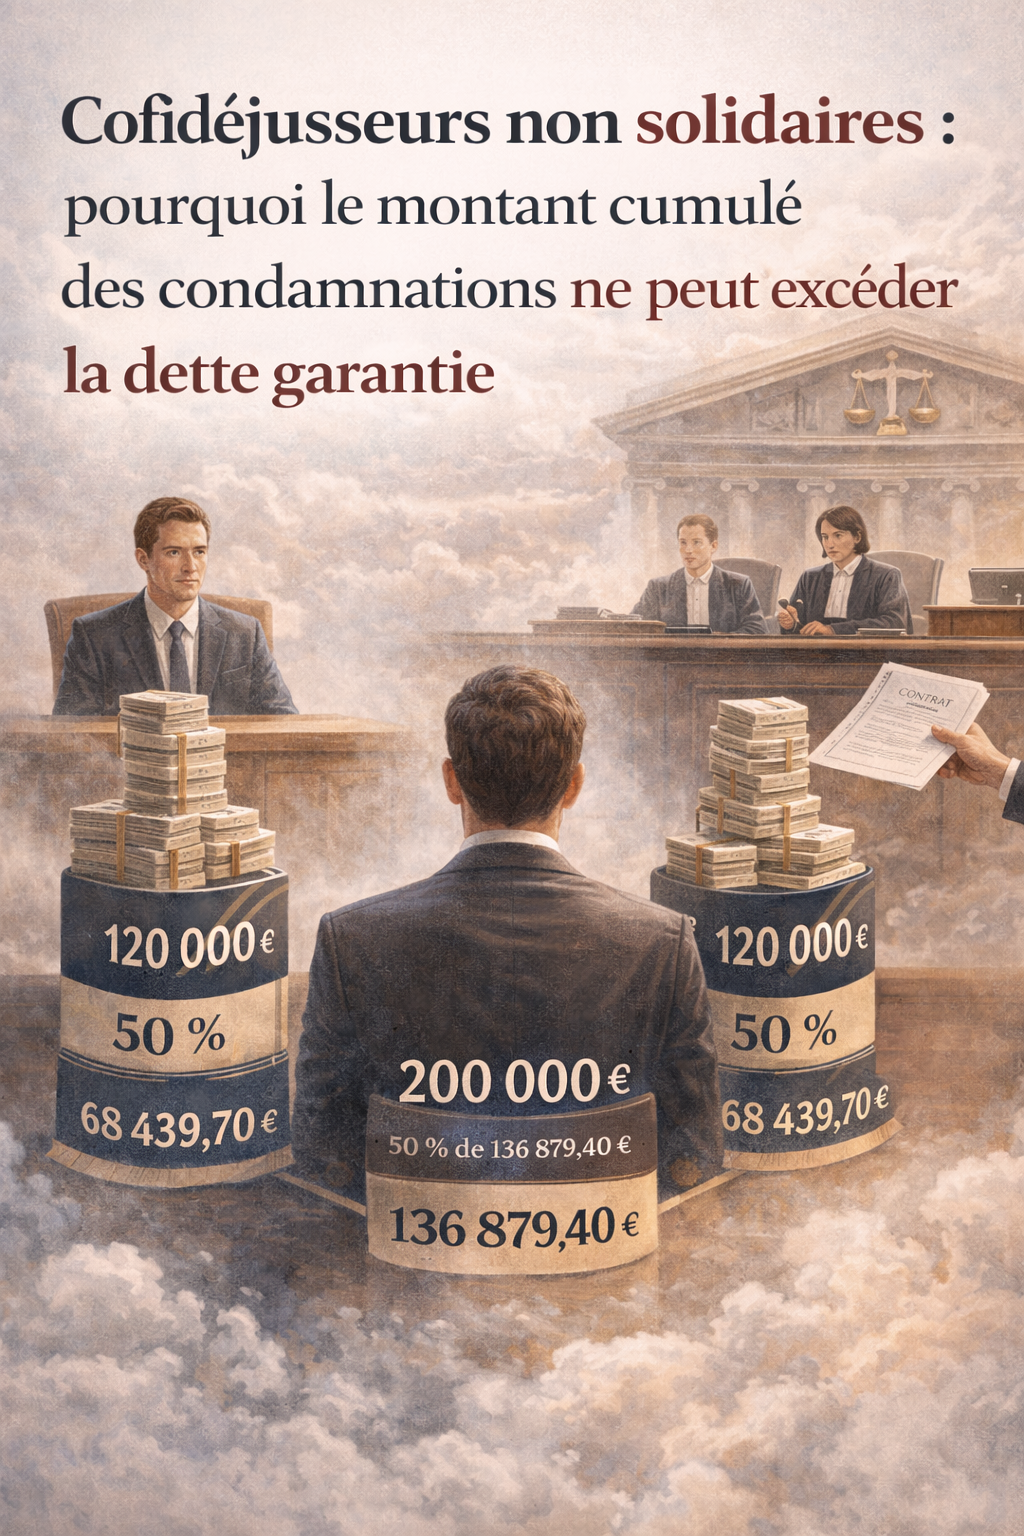
In this case, a bank had granted a loan of €200,000 to a company, guaranteed by two individual sureties each committed up to €120,000. Following the judicial liquidation of the borrowing company, the bank sued both sureties for payment. The outstanding principal debt then stood at €136,879.40. The effect of the company's collective insolvency proceedings on the position of individual sureties is examined in our article on the director's personal guarantee and collective insolvency proceedings.
The lower courts, having found that the co-sureties were not jointly liable, nonetheless ordered each of them to pay €120,000, a total of €240,000 – a sum exceeding the actual amount of the guaranteed debt by more than €103,000.
The quashing: requiring proportionate division
The Commercial Chamber quashes the appeal judgment, stating that "it follows from the combination" of former Articles 2290 and 2302 of the French Civil Code that "the total amount of the sums awarded against the sureties, which must be determined in proportion to their respective undertakings, cannot exceed that of the principal debtor's debt". The Court specifies that this rule applies regardless of whether or not the sureties are jointly liable with the principal debtor.
In concrete terms, the lower courts should have applied the following proportionate division formula:
(Individual surety's undertaking / Total undertakings) × Guaranteed debt
That is, in this case: (120,000 / 240,000) × 136,879.40 = €68,439.70 per surety, for a total consistent with the amount of the guaranteed claim.
A solution transposable under the law resulting from the Ordinance of 15 September 2021
Although the judgment was given on the basis of the texts predating the reform of security law, the solution remains fully applicable under the new law. Articles 2296 and 2306 of the French Civil Code reproduce in substance the provisions of former Articles 2290 and 2302. The third paragraph of new Article 2306 moreover supports the analysis: by reserving the exclusion of the benefit of division solely for "sureties jointly liable with one another" or those who have waived that benefit, it confirms, by a reading a contrario, that co-sureties who are not jointly liable to one another keep that benefit, independently of any joint liability with the principal debtor.
Practical consequences
For creditors
A creditor with the benefit of several non-joint suretyships must build the constraint of proportionate division into its enforcement from the outset. Suing all the co-sureties does not allow recovery of more than the amount of the principal debt. The choice to proceed against only one surety – the most solvent – may prove strategically more effective, it being for that surety then to exercise its recourse against the other co-sureties.
For sureties
Co-sureties who are not jointly liable to one another now have a clearly established defence: where they are sued jointly, they may require that the judgment against each be calculated pro rata to its undertaking, so that the total does not exceed the amount of the guaranteed debt. This protection applies even where they are jointly liable with the principal debtor. On another defence frequently debated between bank and surety, see our analysis of the manifestly disproportionate suretyship.
For drafters of deeds
Stipulating joint liability between co-sureties remains the surest means for the creditor to avoid the application of proportionate division. Failing that, suretyship deeds must be drafted so as to anticipate this constraint, by calibrating the undertaking amounts accordingly.
Identified litigation risks
- Risk of overpayment: a creditor that has obtained judgments exceeding the principal debt is exposed to an action for recovery of undue payment or to the quashing of the judgment.
- Risk of challenge to past judgments: sureties already ordered to pay in similar circumstances might rely on this judgment to challenge retroactively the amount of the awards.
- Drafting risk: the absence of a joint liability clause between co-sureties exposes the creditor to a significant reduction in the amount recoverable from each surety.
- Risk of miscalculating the division: where the co-sureties' undertakings are unequal, the proportionate formula requires a rigorous calculation that the lower courts will have to master.
Strategies and recommendations
For creditors and their advisers
- Systematically check for a horizontal joint liability clause before any proceedings against the co-sureties.
- In the absence of joint liability, favour an action against a single surety for the maximum amount of its undertaking, rather than a joint claim resulting in a division.
- Include, in loan documents secured by several suretyships, an express clause of joint liability between co-sureties (Article 2306, paragraph 3, French Civil Code).
For sureties and their advisers
- Where sued jointly, raise immediately the argument based on proportionate division and ask the court to calculate each co-surety's share according to the formula endorsed by the Cour de cassation.
- Check that judgments already given comply with this rule and, failing that, consider the appropriate avenues of appeal.
Conclusion
The judgment of 1 April 2026 strongly reaffirms the accessory nature of suretyship where co-sureties are not jointly liable to one another. The creditor cannot receive, through multiple judgments, more than the principal debtor owes. This solution, applicable both under the former law and under the regime resulting from the Ordinance of 15 September 2021, requires practitioners to exercise heightened vigilance in drafting security documents and in conducting recovery proceedings.
Quatre questions suffisent à situer votre position, le délai qui vous reste et ce qu'il faut vérifier en priorité. Vous décidez ensuite si vous en parlez au cabinet.
Décrire ma situationA question about your own situation?
The firm assists business owners, investors and private individuals, from upstream advice through to litigation.


